One need only examine the underlying appointment authority of the FHFA Director to understand the changes that went into effect yesterday on Fannie Mae and Freddie Mac mortgage loans. Under a recent Supreme Court ruling the FHFA Director is now an at-will appointee of the President. This means the Director will come and go with new Presidents and must be responsive to the current President’s agenda.
Under the administration’s agenda of housing affordability, the May 1st changes to loans received by the GSE’s results in riskier borrowers with lower fico scores paying less and those with a higher fico will pay more. The GSE’s can mitigate some of this risk by utilizing credit risk transfer and mortgage insurance. Of course, it’s hard to believe that the re-insurance market will dip into CRT deals with 640 fico scores.
Watch closely as lack of legislative solutions on housing affordability push this and new administrations to carryout their agendas via FHFA and HUD. Policies may increasingly be whipsawed as leadership rotates more quickly.
Related Posts
Private Credit Just Became a Receivership Issue
The promise of life insurance is simple: protection when it matters most. Policyholders pay premiums…
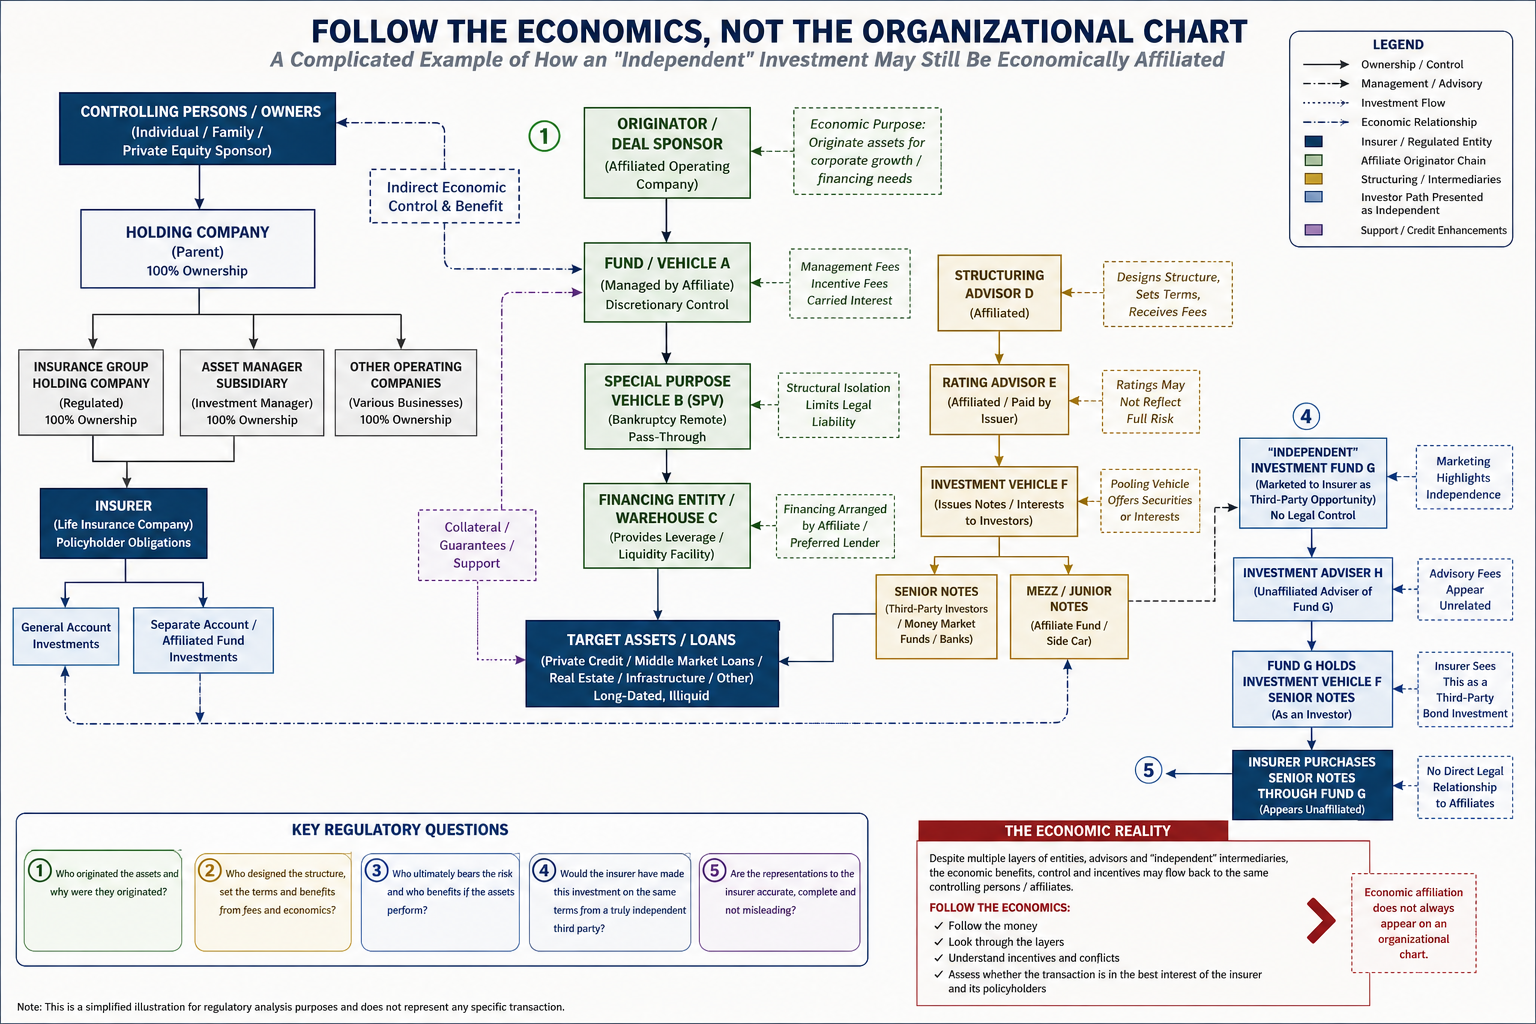
When Is an Insurance Investment Really an Affiliate Transaction?
The TWG–Delaware Life controversy exposes a regulatory problem that goes far beyond one insurer: legal…
Is the AI Boom Migrating Onto Life Insurers’ Balance Sheets?
The promise of life insurance is simple: protection when it matters most. Policyholders pay premiums…
AI Prompts Are Becoming Discoverable: A Turning Point for Expert Witnesses
The promise of life insurance is simple: protection when it matters most. Policyholders pay premiums…